
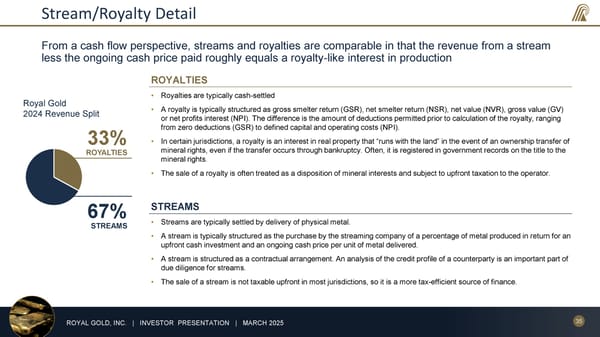
35 ROYAL GOLD, INC. | INVESTOR PRESENTATION | MARCH 2025 Stream/Royalty Detail ROYALTIES • Royalties are typically cash-settled • A royalty is typically structured as gross smelter return (GSR), net smelter return (NSR), net value (NVR), gross value (GV) or net profits interest (NPI). The difference is the amount of deductions permitted prior to calculation of the royalty, ranging from zero deductions (GSR) to defined capital and operating costs (NPI). • In certain jurisdictions, a royalty is an interest in real property that “runs with the land” in the event of an ownership transfer of mineral rights, even if the transfer occurs through bankruptcy. Often, it is registered in government records on the title to the mineral rights. • The sale of a royalty is often treated as a disposition of mineral interests and subject to upfront taxation to the operator. STREAMS • Streams are typically settled by delivery of physical metal. • A stream is typically structured as the purchase by the streaming company of a percentage of metal produced in return for an upfront cash investment and an ongoing cash price per unit of metal delivered. • A stream is structured as a contractual arrangement. An analysis of the credit profile of a counterparty is an important part of due diligence for streams. • The sale of a stream is not taxable upfront in most jurisdictions, so it is a more tax-efficient source of finance. STREAMS 67% ROYALTIES 33% Royal Gold 2024 Revenue Split From a cash flow perspective, streams and royalties are comparable in that the revenue from a stream less the ongoing cash price paid roughly equals a royalty-like interest in production
 March 2025 Investor Presentation Page 34 Page 36