
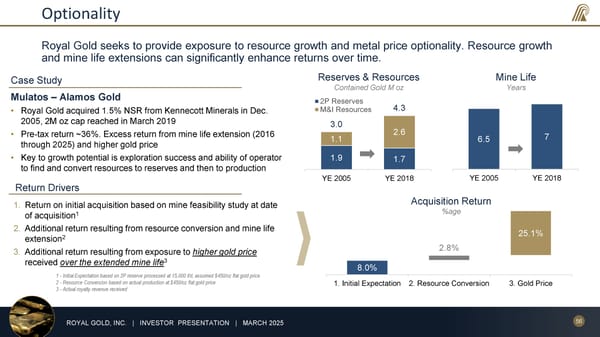
56 ROYAL GOLD, INC. | INVESTOR PRESENTATION | MARCH 2025 8.0% 2.8% 25.1% 1. Initial Expectation 2. Resource Conversion 3. Gold Price Optionality Case Study Mulatos – Alamos Gold • Royal Gold acquired 1.5% NSR from Kennecott Minerals in Dec. 2005, 2M oz cap reached in March 2019 • Pre-tax return ~36%. Excess return from mine life extension (2016 through 2025) and higher gold price • Key to growth potential is exploration success and ability of operator to find and convert resources to reserves and then to production 1.9 1.7 1.1 2.6 3.0 4.3 YE 2005 YE 2018 2P Reserves M&I Resources 6.5 7 YE 2005 YE 2018 Reserves & Resources Contained Gold M oz Mine Life Years Acquisition Return %age 1 - Initial Expectation based on 2P reserve processed at 15,000 t/d, assumed $450/oz flat gold price 2 - Resource Conversion based on actual production at $450/oz flat gold price 3 - Actual royalty revenue received 1. Return on initial acquisition based on mine feasibility study at date of acquisition 1 2. Additional return resulting from resource conversion and mine life extension 2 3. Additional return resulting from exposure to higher gold price received over the extended mine life 3 Return Drivers Royal Gold seeks to provide exposure to resource growth and metal price optionality. Resource growth and mine life extensions can significantly enhance returns over time.
 March 2025 Investor Presentation Page 55 Page 57