
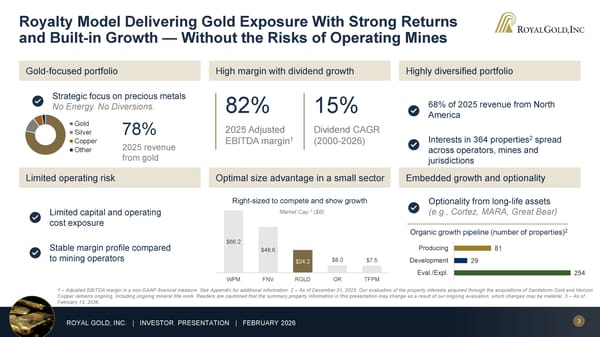
3 ROYAL GOLD, INC. | INVESTOR PRESENTATION | FEBRUARY 2026 81 29 254 Producing Development Eval./Expl. 82% 2025 Adjusted EBITDA margin 1 68% of 2025 revenue from North America Interests in 364 properties 2 spread across operators, mines and jurisdictions Optionality from long-life assets (e.g., Cortez, MARA, Great Bear) High margin with dividend growth Highly diversified portfolio Optimal size advantage in a small sector Embedded growth and optionality Gold-focused portfolio Limited capital and operating cost exposure Stable margin profile compared to mining operators Limited operating risk Gold Silver Copper Other Strategic focus on precious metals No Energy. No Diversions. 2025 revenue from gold 15% Dividend CAGR (2000-2026) $66.2 $48.6 $24.2 $8.0 $7.5 WPM FNV RGLD OR TFPM Right-sized to compete and show growth Market Cap. 3 ($B) 78% 1 – Adjusted EBITDA margin is a non-GAAP financial measure. See Appendix for additional information. 2 – As of December 31, 2025. Our evaluation of the property interests acquired through the acquisitions of Sandstorm Gold and Horizon Copper remains ongoing, including ongoing mineral title work. Readers are cautioned that the summary property information in this presentation may change as a result of our ongoing evaluation, which changes may be material. 3 – As of February 13, 2026. Royalty Model Delivering Gold Exposure With Strong Returns and Built-in Growth — Without the Risks of Operating Mines Organic growth pipeline (number of properties) 2
 February 2026 Investor Presentation Page 2 Page 4