
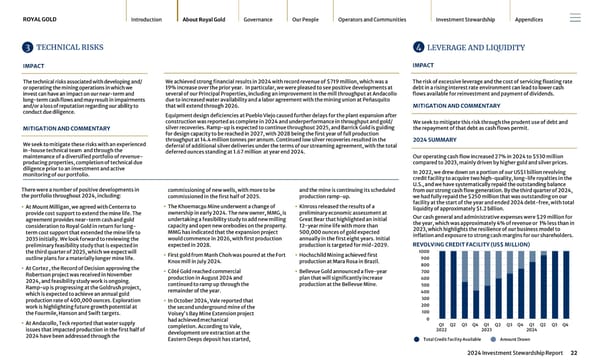
3 TECHNICAL RISKS IMPACT The technical risks associated with developing and/ or operating the mining operations in which we invest can have an impact on our near-term and long-term cash flows and may result in impairments and/or a loss of reputation regarding our ability to conduct due diligence. MITIGATION AND COMMENTARY We seek to mitigate these risks with an experienced in-house technical team and through the maintenance of a diversified portfolio of revenue- producing properties, completion of technical due diligence prior to an investment and active monitoring of our portfolio. We achieved strong financial results in 2024 with record revenue of $719 million, which was a 19% increase over the prior year. In particular, we were pleased to see positive developments at several of our Principal Properties, including an improvement in the mill throughput at Andacollo due to increased water availability and a labor agreement with the mining union at Peñasquito that will extend through 2026. Equipment design deficiencies at Pueblo Viejo caused further delays for the plant expansion after construction was reported as complete in 2024 and underperformance in throughput and gold/ silver recoveries. Ramp-up is expected to continue throughout 2025, and Barrick Gold is guiding for design capacity to be reached in 2027, with 2028 being the first year of full production throughput at 14.4 million tonnes per annum. Continued low silver recoveries resulted in the deferral of additional silver deliveries under the terms of our streaming agreement, with the total deferred ounces standing at 1.67 million at year end 2024. ROYAL GOLD Introduction About Royal Gold Governance Our People Operators and Communities Investment Stewardship Appendices 2024 Investment Stewardship Report 22 There were a number of positive developments in the portfolio throughout 2024, including: • At Mount Milligan, we agreed with Centerra to provide cost support to extend the mine life. The agreement provides near-term cash and gold consideration to Royal Gold in return for long- term cost support that extended the mine life to 2035 initially. We look forward to reviewing the preliminary feasibility study that is expected in the third quarter of 2025, which we expect will outline plans for a materially longer mine life. • At Cortez , the Record of Decision approving the Robertson project was received in November 2024, and feasibility study work is ongoing. Ramp-up is progressing at the Goldrush project, which is expected to achieve an annual gold production rate of 400,000 ounces. Exploration work is highlighting future growth potential at the Fourmile, Hanson and Swift targets. • At Andacollo, Teck reported that water supply issues that impacted production in the first half of 2024 have been addressed through the commissioning of new wells, with more to be commissioned in the first half of 2025. • The Khoemacau Mine underwent a change of ownership in early 2024. The new owner, MMG, is undertaking a feasibility study to add new milling capacity and open new orebodies on the property. MMG has indicated that the expansion project would commence in 2026, with first production expected in 2028. • First gold from Manh Choh was poured at the Fort Knox mill in July 2024. • Côté Gold reached commercial production in August 2024 and continued to ramp up through the remainder of the year. • In October 2024, Vale reported that the second underground mine of the Voisey's Bay Mine Extension project had achieved mechanical completion. According to Vale, development ore extraction at the Eastern Deeps deposit has started, and the mine is continuing its scheduled production ramp-up. • Kinross released the results of a preliminary economic assessment at Great Bear that highlighted an initial 12-year mine life with more than 500,000 ounces of gold expected annually in the first eight years. Initial production is targeted for mid-2029. • Hochschild Mining achieved first production at Mara Rosa in Brazil. • Bellevue Gold announced a five-year plan that will significantly increase production at the Bellevue Mine. 4 LEVERAGE AND LIQUIDITY IMPACT The risk of excessive leverage and the cost of servicing floating rate debt in a rising interest rate environment can lead to lower cash flows available for reinvestment and payment of dividends. MITIGATION AND COMMENTARY We seek to mitigate this risk through the prudent use of debt and the repayment of that debt as cash flows permit. 2024 SUMMARY Our operating cash flow increased 27% in 2024 to $530 million compared to 2023, mainly driven by higher gold and silver prices. In 2022, we drew down on a portion of our US$1 billion revolving credit facility to acquire two high-quality, long-life royalties in the U.S., and we have systematically repaid the outstanding balance from our strong cash flow generation. By the third quarter of 2024, we had fully repaid the $250 million that was outstanding on our facility at the start of the year and ended 2024 debt-free, with total liquidity of approximately $1.2 billion. Our cash general and administrative expenses were $29 million for the year, which was approximately 4% of revenue or 1% less than in 2023, which highlights the resilience of our business model to inflation and exposure to strong cash margins for our shareholders. REVOLVING CREDIT FACILITY (US$ MILLION) Q1 2022 Q2 Q3 Q4 Q1 2023 Q2 Q3 Q4 Q1 2024 Q2 Q3 Q4 0 100 200 300 400 500 600 700 800 900 1000 Total Credit Facility Available Amount Drawn
 2024 Investment Stewardship Report Page 21 Page 23