
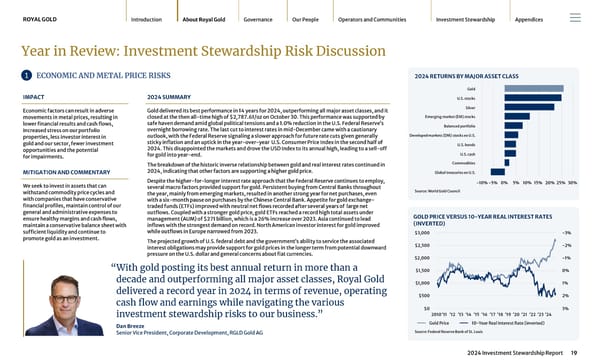
Year in Review: Investment Stewardship Risk Discussion 1 ECONOMIC AND METAL PRICE RISKS IMPACT Economic factors can result in adverse movements in metal prices, resulting in lower financial results and cash flows, increased stress on our portfolio properties, less investor interest in gold and our sector, fewer investment opportunities and the potential for impairments. MITIGATION AND COMMENTARY We seek to invest in assets that can withstand commodity price cycles and with companies that have conservative financial profiles, maintain control of our general and administrative expenses to ensure healthy margins and cash flows, maintain a conservative balance sheet with sufficient liquidity and continue to promote gold as an investment. 2024 SUMMARY Gold delivered its best performance in 14 years for 2024, outperforming all major asset classes, and it closed at the then all-time high of $2,787.61/oz on October 30. This performance was supported by safe haven demand amid global political tensions and a 1.0% reduction in the U.S. Federal Reserve’s overnight borrowing rate. The last cut to interest rates in mid-December came with a cautionary outlook, with the Federal Reserve signaling a slower approach for future rate cuts given generally sticky inflation and an uptick in the year-over-year U.S. Consumer Price Index in the second half of 2024. This disappointed the markets and drove the USD Index to its annual high, leading to a sell-off for gold into year-end. The breakdown of the historic inverse relationship between gold and real interest rates continued in 2024, indicating that other factors are supporting a higher gold price. Despite the higher-for-longer interest rate approach that the Federal Reserve continues to employ, several macro factors provided support for gold. Persistent buying from Central Banks throughout the year, mainly from emerging markets, resulted in another strong year for net purchases, even with a six-month pause on purchases by the Chinese Central Bank. Appetite for gold exchange- traded funds (ETFs) improved with neutral net flows recorded after several years of large net outflows. Coupled with a stronger gold price, gold ETFs reached a record high total assets under management (AUM) of $271 billion, which is a 26% increase over 2023. Asia continued to lead inflows with the strongest demand on record. North American investor interest for gold improved while outflows in Europe narrowed from 2023. The projected growth of U.S. federal debt and the government’s ability to service the associated interest obligations may provide support for gold prices in the longer term from potential downward pressure on the U.S. dollar and general concerns about fiat currencies. “With gold posting its best annual return in more than a decade and outperforming all major asset classes, Royal Gold delivered a record year in 2024 in terms of revenue, operating cash flow and earnings while navigating the various investment stewardship risks to our business.” Dan Breeze Senior Vice President, Corporate Development, RGLD Gold AG 2024 Investment Stewardship Report 19 ROYAL GOLD Introduction About Royal Gold Governance Our People Operators and Communities Investment Stewardship Appendices -10% -5% 0% 5% 10% 15% 20% 25% 30% Gold U.S. stocks Silver Emerging market (EM) stocks Balanced portfolio Developed markets (DM) stocks ex U.S. U.S. bonds U.S. cash Commodities Global treasuries ex U.S. Source: World Gold Council 2024 RETURNS BY MAJOR ASSET CLASS 2010 ‘11 ‘12 ‘13 ‘14 ‘15 ‘16 ‘17 ‘18 ‘19 ‘20 ‘21 ‘22 ‘23 ‘24 $0 $500 $1,000 $1,500 $2,000 $2,500 $3,000 -3% -2% -1% 0% 1% 2% 3% Gold Price 10-Year Real Interest Rate (inverted) Source: Federal Reserve Bank of St. Louis GOLD PRICE VERSUS 10-YEAR REAL INTEREST RATES (INVERTED)
 2024 Investment Stewardship Report Page 18 Page 20